Brief
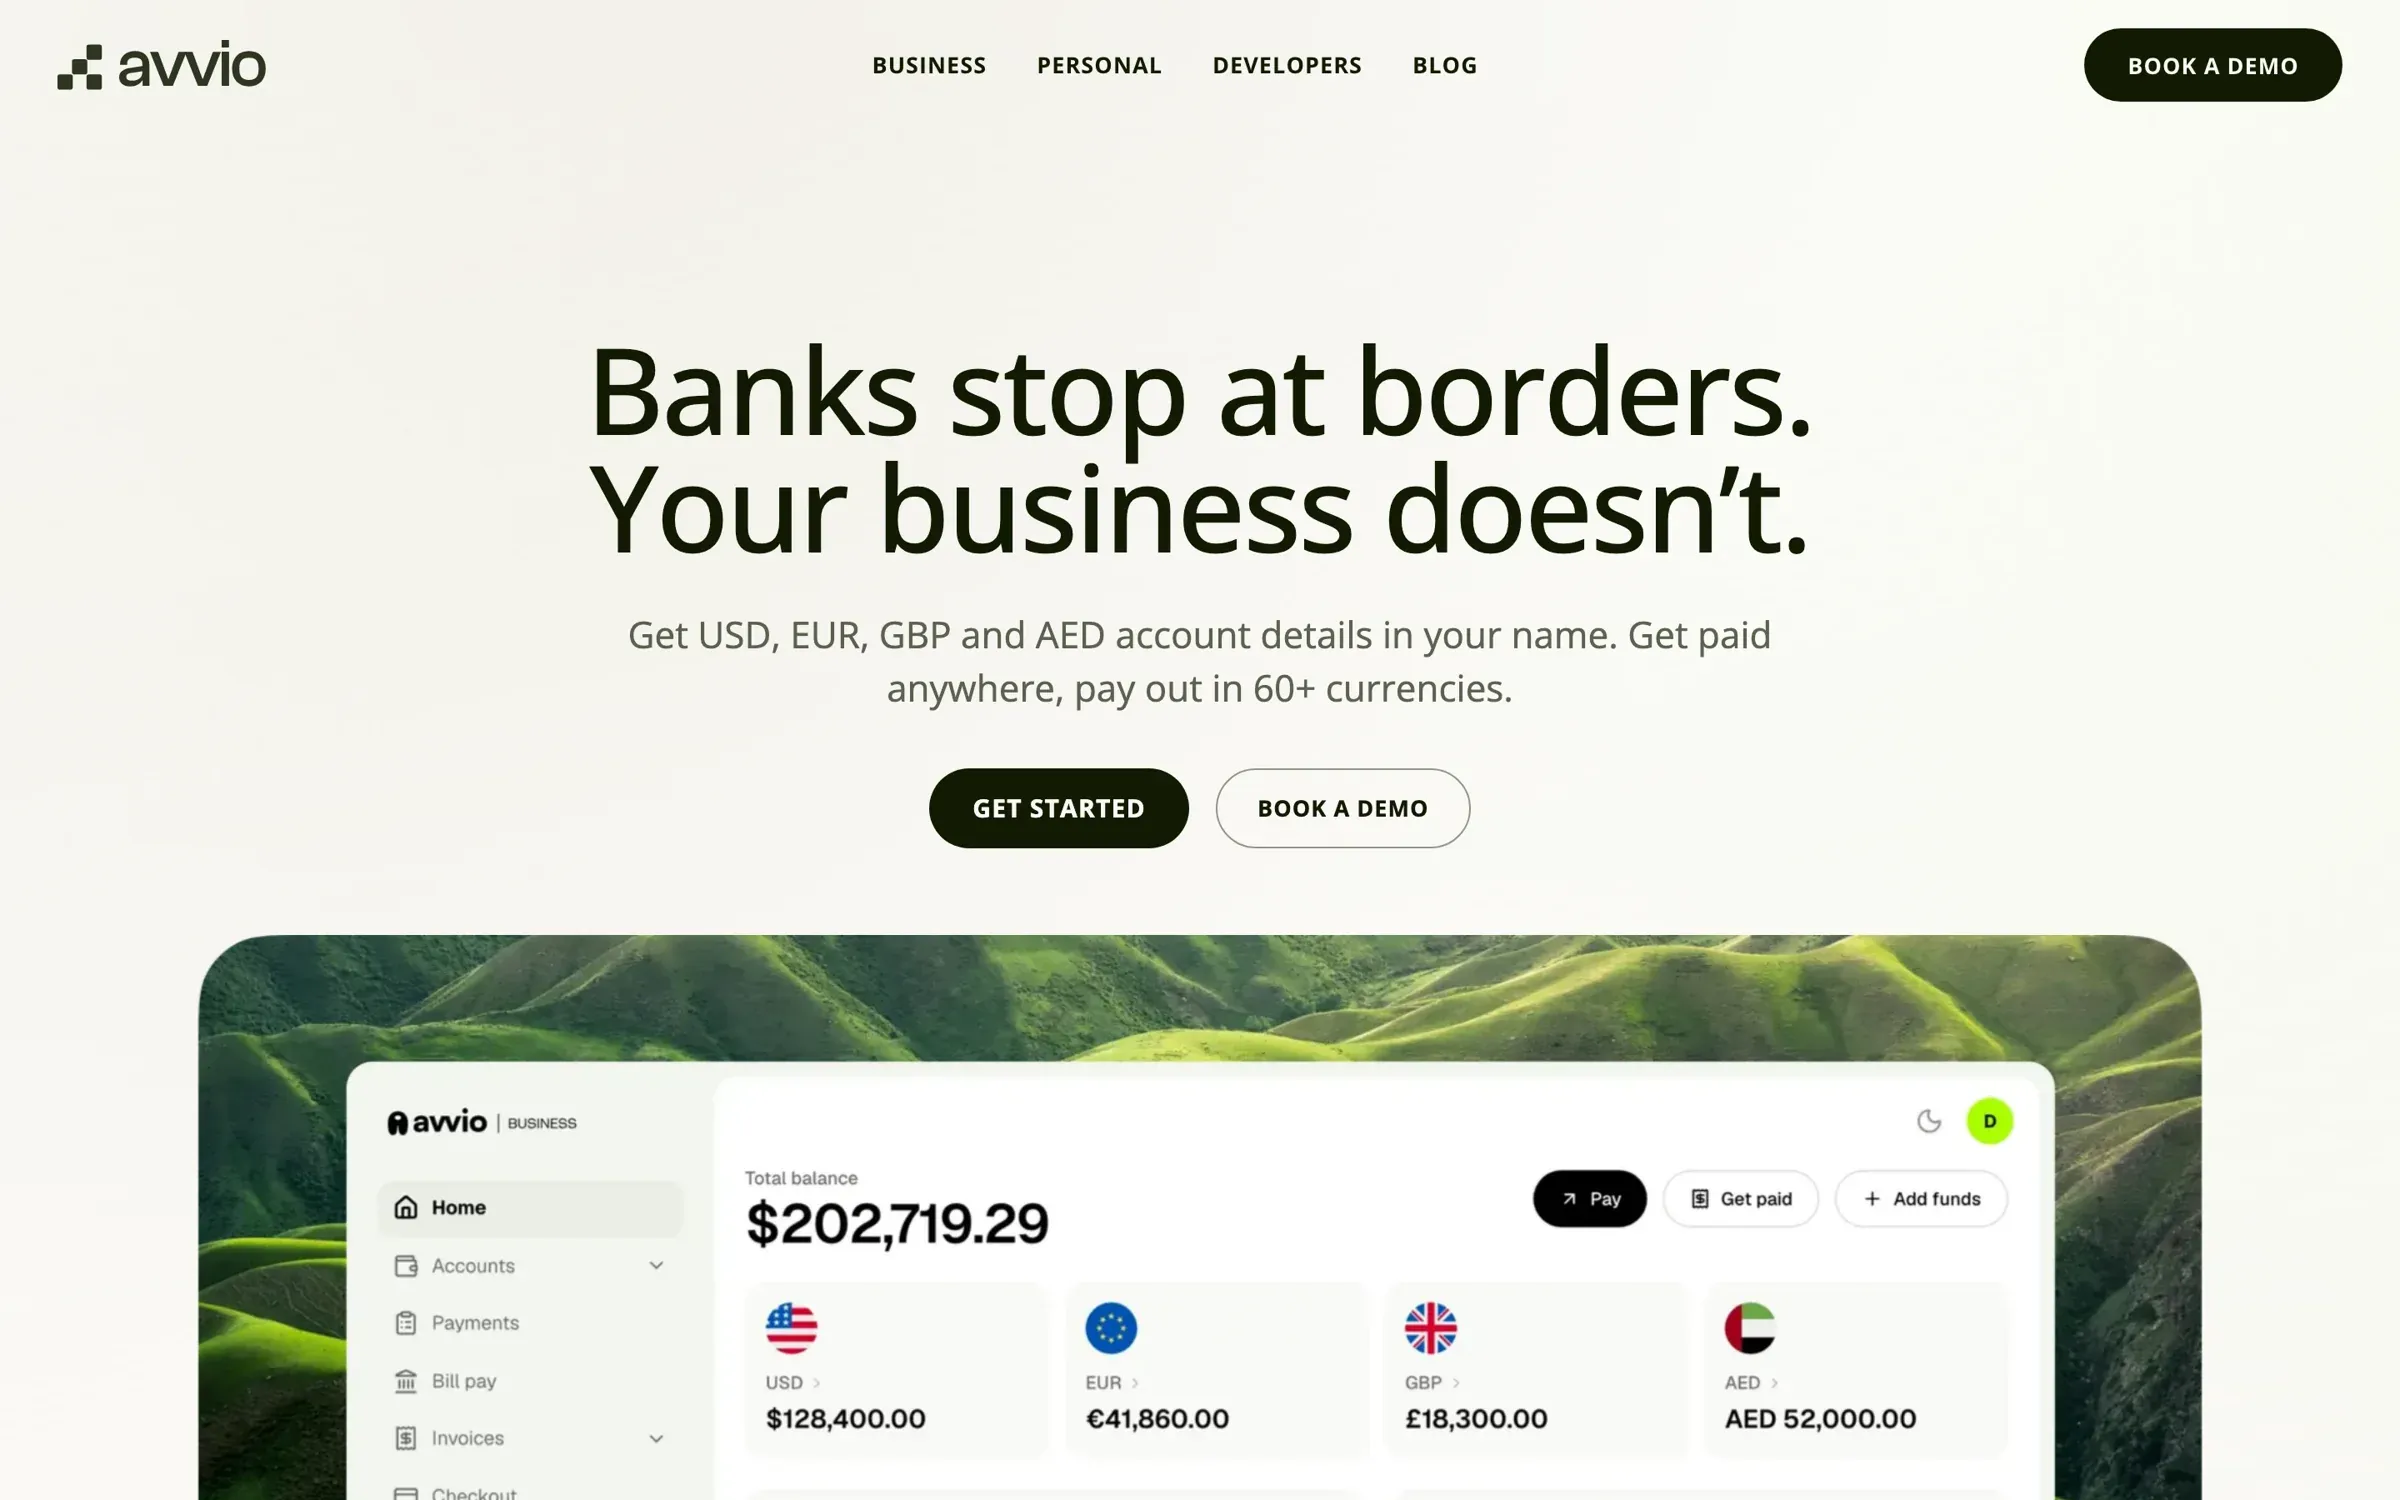
Banks stop at borders. Your business doesn’t.
Avvio started as a consumer app: black, neon lime, loud. Businesses need something else. A finance lead choosing who moves payroll to contractors in a dozen countries is buying calm, control and proof that the money is safe.
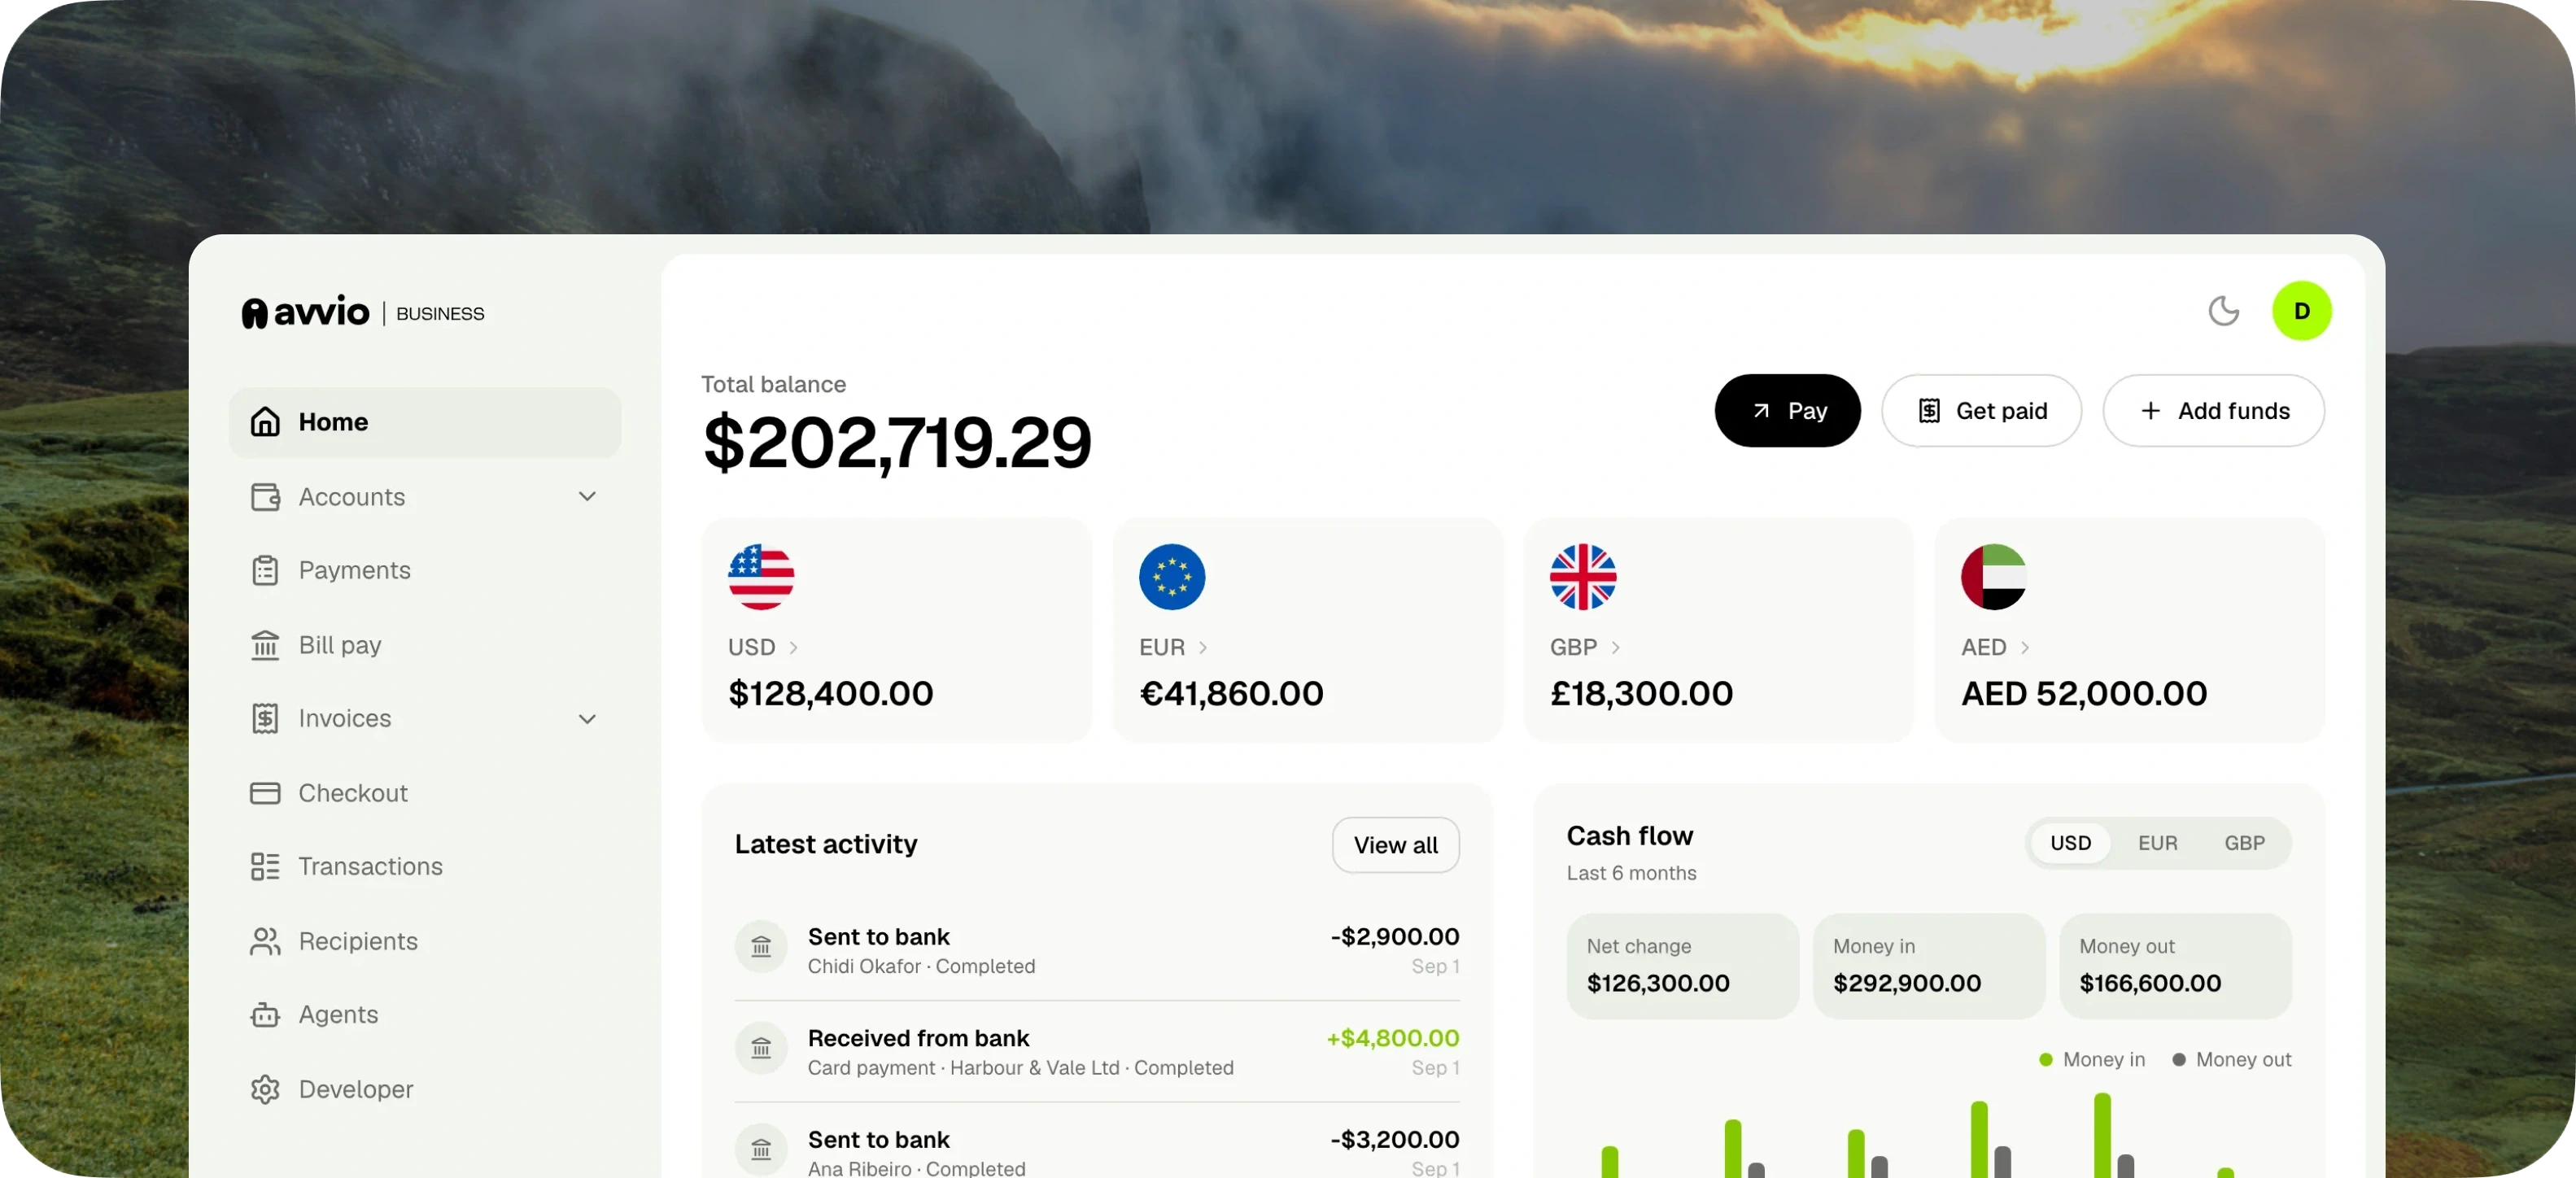
So Avvio Business got its own system inside the same family: warm, quiet greens, plain language, and one saturated colour kept for the product itself. I designed the identity, wrote the guidelines, and designed the website and product on top of them.
01 Strategy
Three doors, one ledger
The same rails and the same ledger sit under three products, so I designed them as three doors into one system rather than three brands:
- Business: receive payments in USD, EUR, GBP and AED in the company’s name, and pay out anywhere.
- Personal: get paid like a local, with USD, EUR and GBP accounts.
- API: accounts, checkout links and payouts inside someone else’s product. Their users never see Avvio.
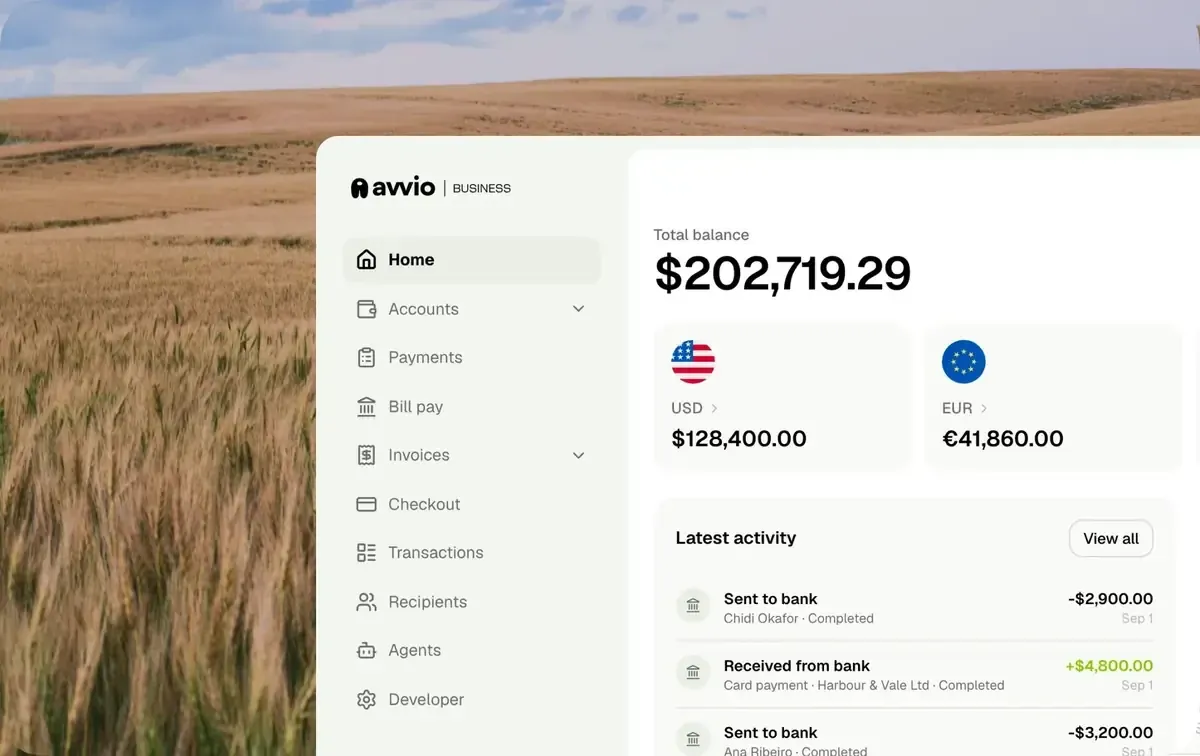
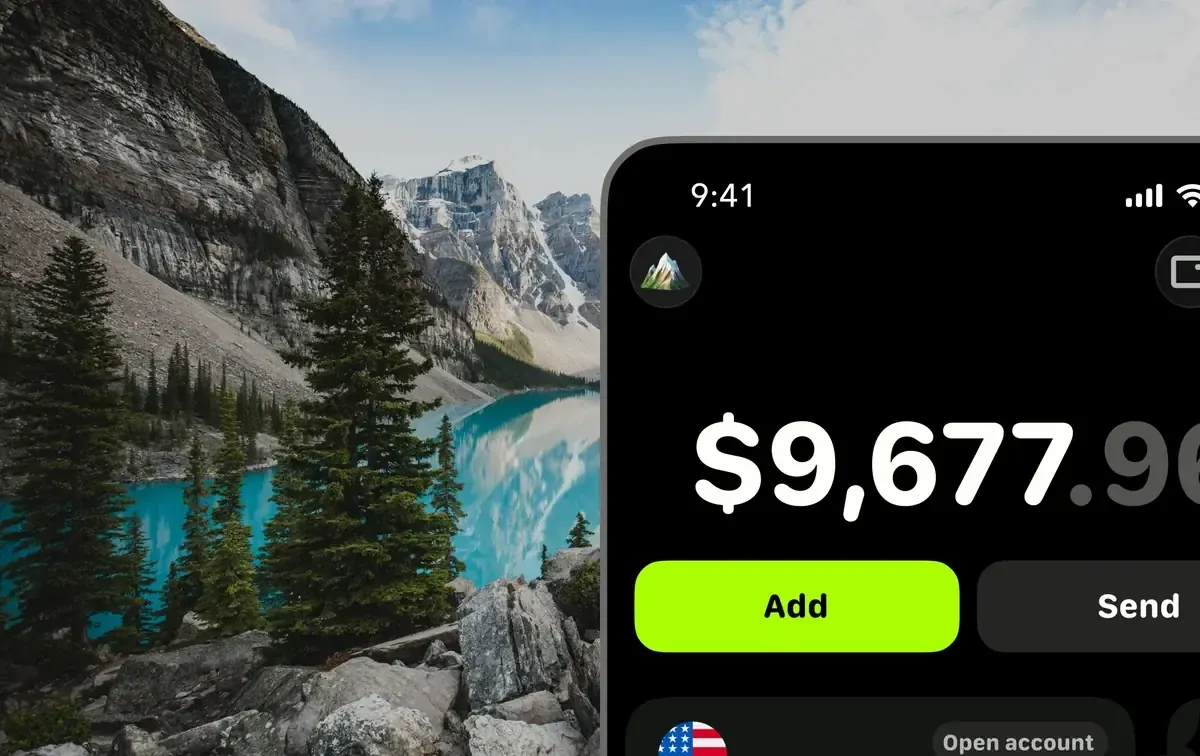
Each door gets its own landscape: wide open places instead of stock offices, because the business can operate from anywhere.
02 Logo
The mark
Four rounded squares on a three-by-three grid: three on the diagonal, one at bottom-right. It reads as money moving through a system and settling, and it works on its own at 16px.
Four lockups cover every ground, plus a light and a dark app icon. Each file has a job, so nobody has to guess.

- Construction
- Four rounded squares on a three-by-three grid: three on the diagonal, one at bottom-right.
- Clear space
- One square on all sides, measured from the squares, not the wordmark.
- Minimum size
- Mark alone 16px. Full lockup 90px wide.
- On photography
- Light file over the darkest part of the frame, or off the image.
03 Colour
Six greens, one lime
A single hue family from near-black to off-white, so every page feels like the same company. Lime is not part of the ramp. It belongs to product interfaces and is the only saturated colour in the system.
The proportion matters as much as the values: roughly 56% cream, 24% bone, 12% ink. A page that is mostly olive or mostly sage is off, even when every value in it is correct.
Proportion on a page
04 Type
One family, set with discipline
Open Sans carries the brand, with a monospace for labels. It is free and works on every platform the brand publishes to, which matters more for a fintech than a bespoke face.
The rules do the work: headlines in medium weight and sentence case, ending in a full stop. Labels in uppercase monospace. Extrabold reserved for figures that carry a claim, always with tabular numbers.
Eyebrow · monospace, uppercase, sage
Banks stop at borders. Your business doesn’t.
Get USD, EUR, GBP and AED account details in your name. Get paid anywhere, pay out in 60+ currencies.
- AaRegular 400 · body
- AaMedium 500 · headlines
- AaBold 700 · buttons
- AaExtrabold 800 · numbers
- AaMonospace · labels
05 Rules
What breaks the mark
Guidelines only work if the misuse is obvious. No recoloured squares, gradients, outlines or rotation. Primary buttons are ink on light grounds and cream on dark ones, never lime, because lime fails contrast as text.
06 Payments
Money in and money out, on one timeline
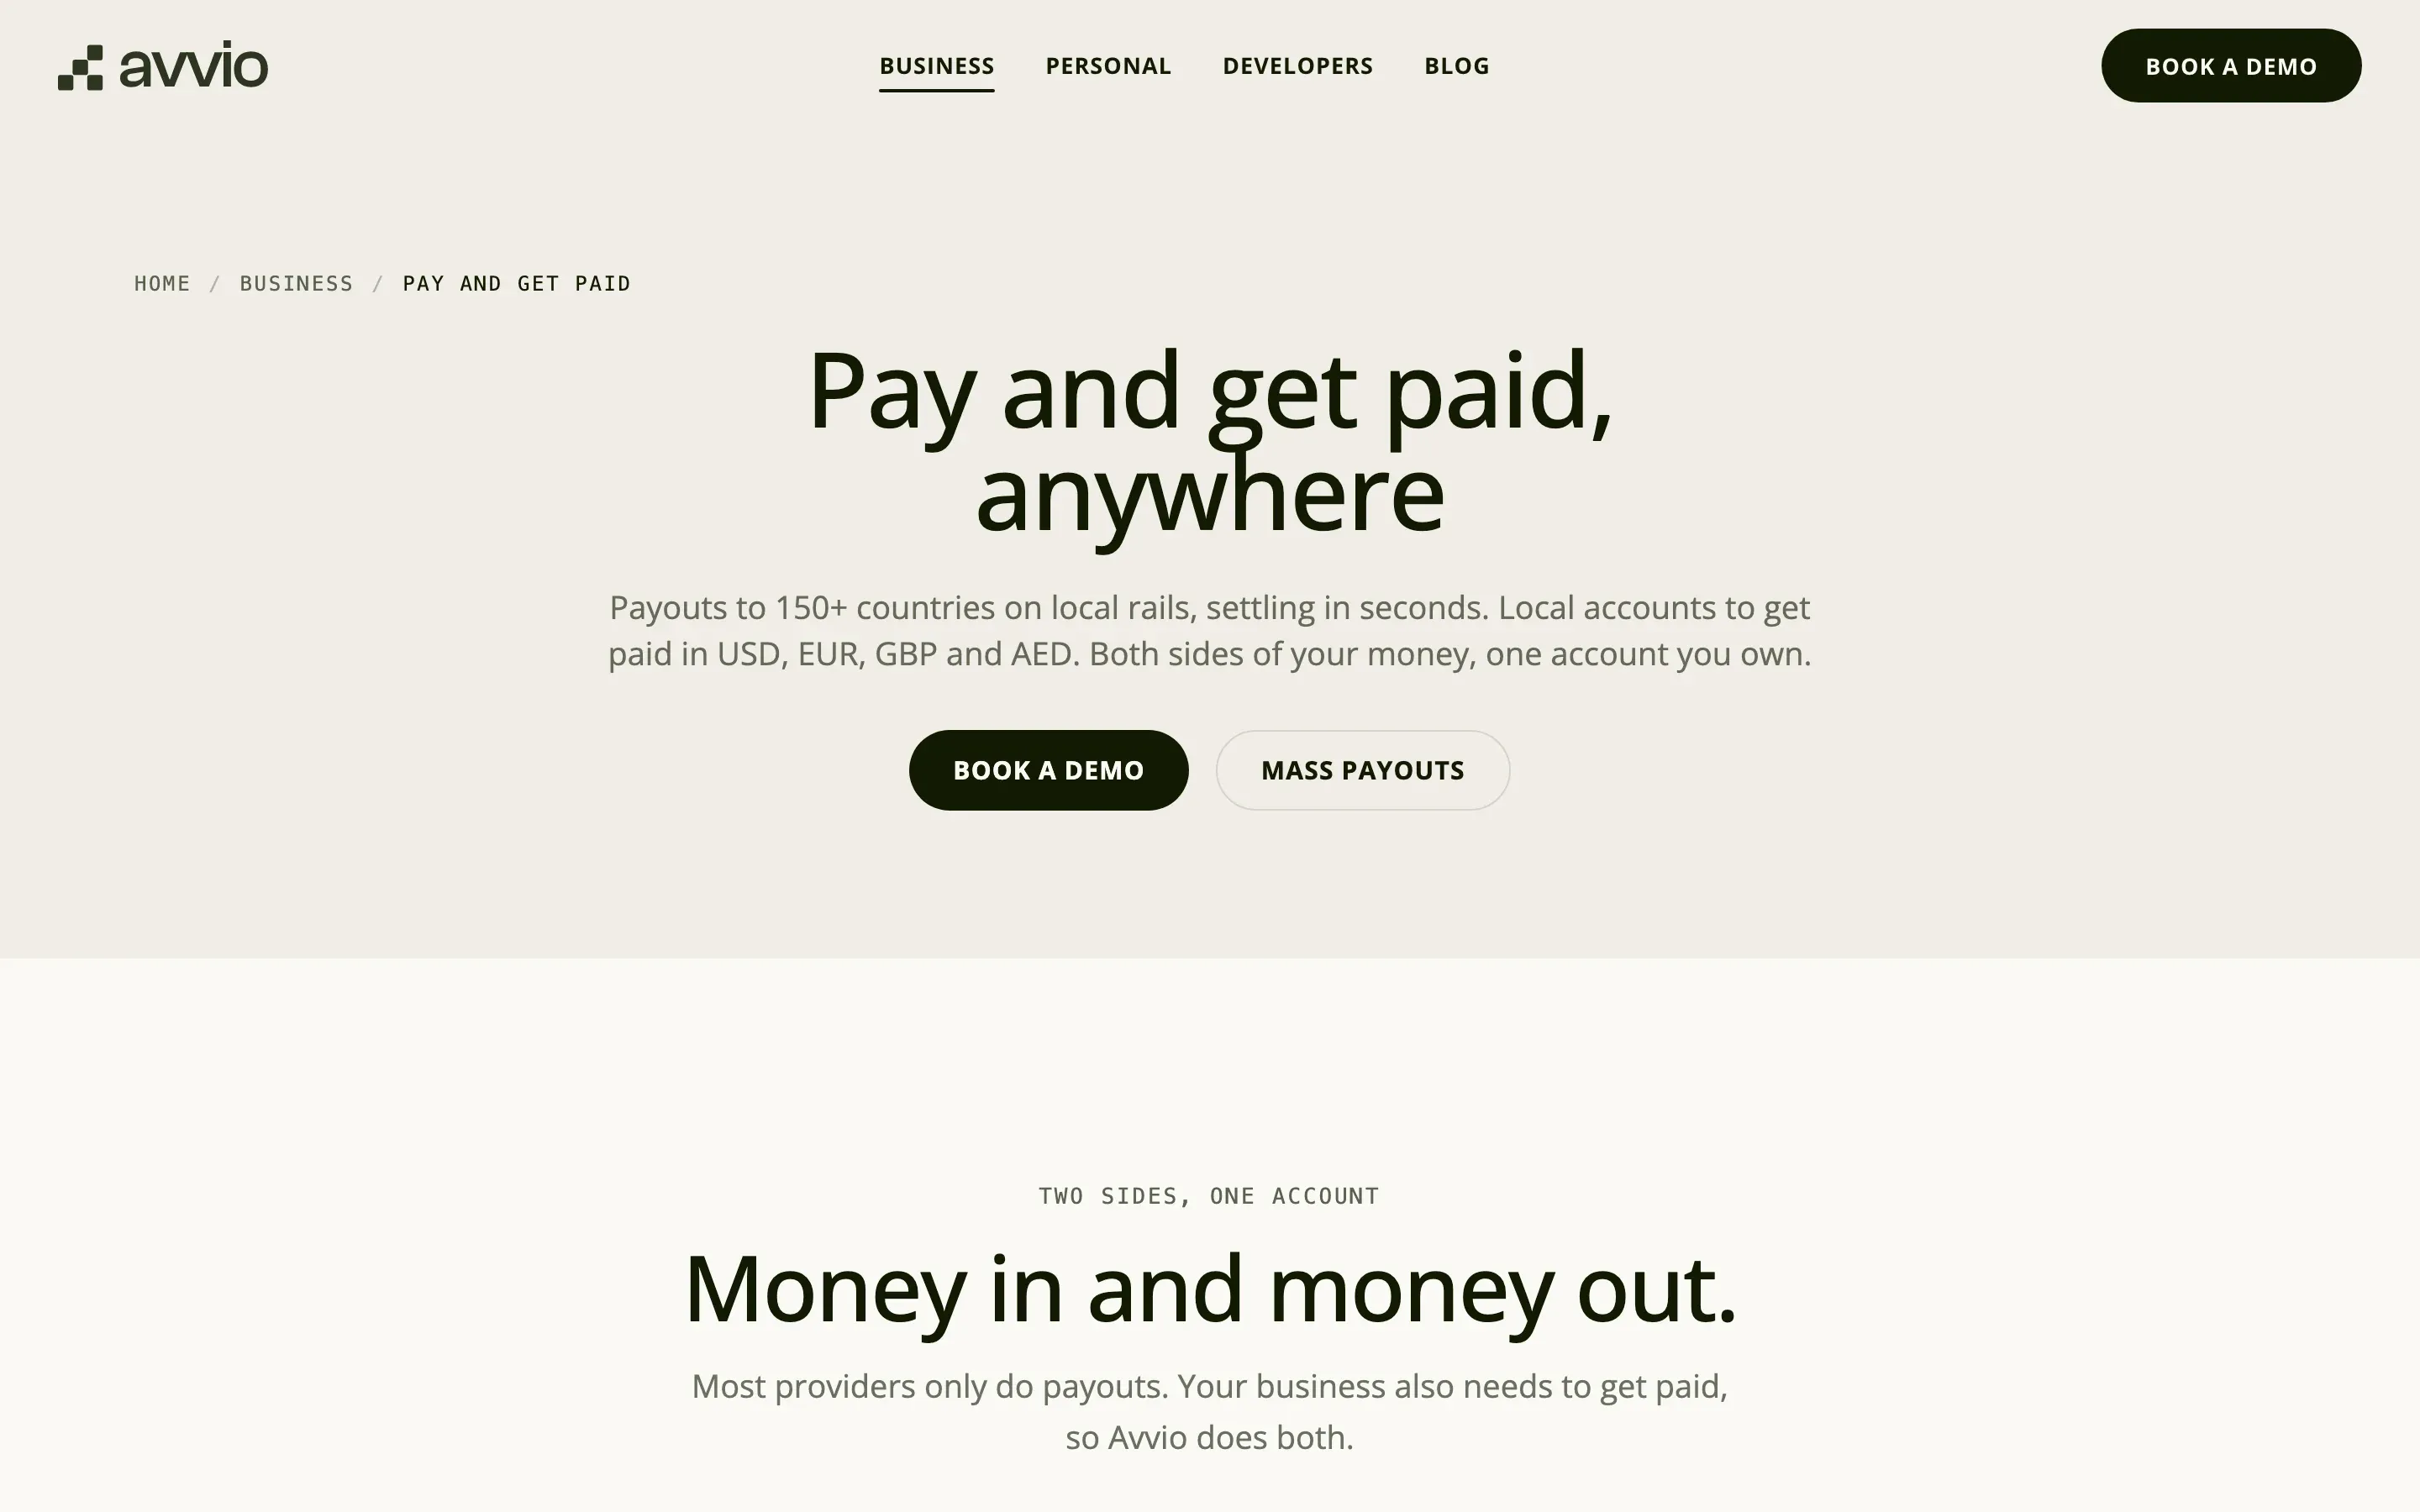
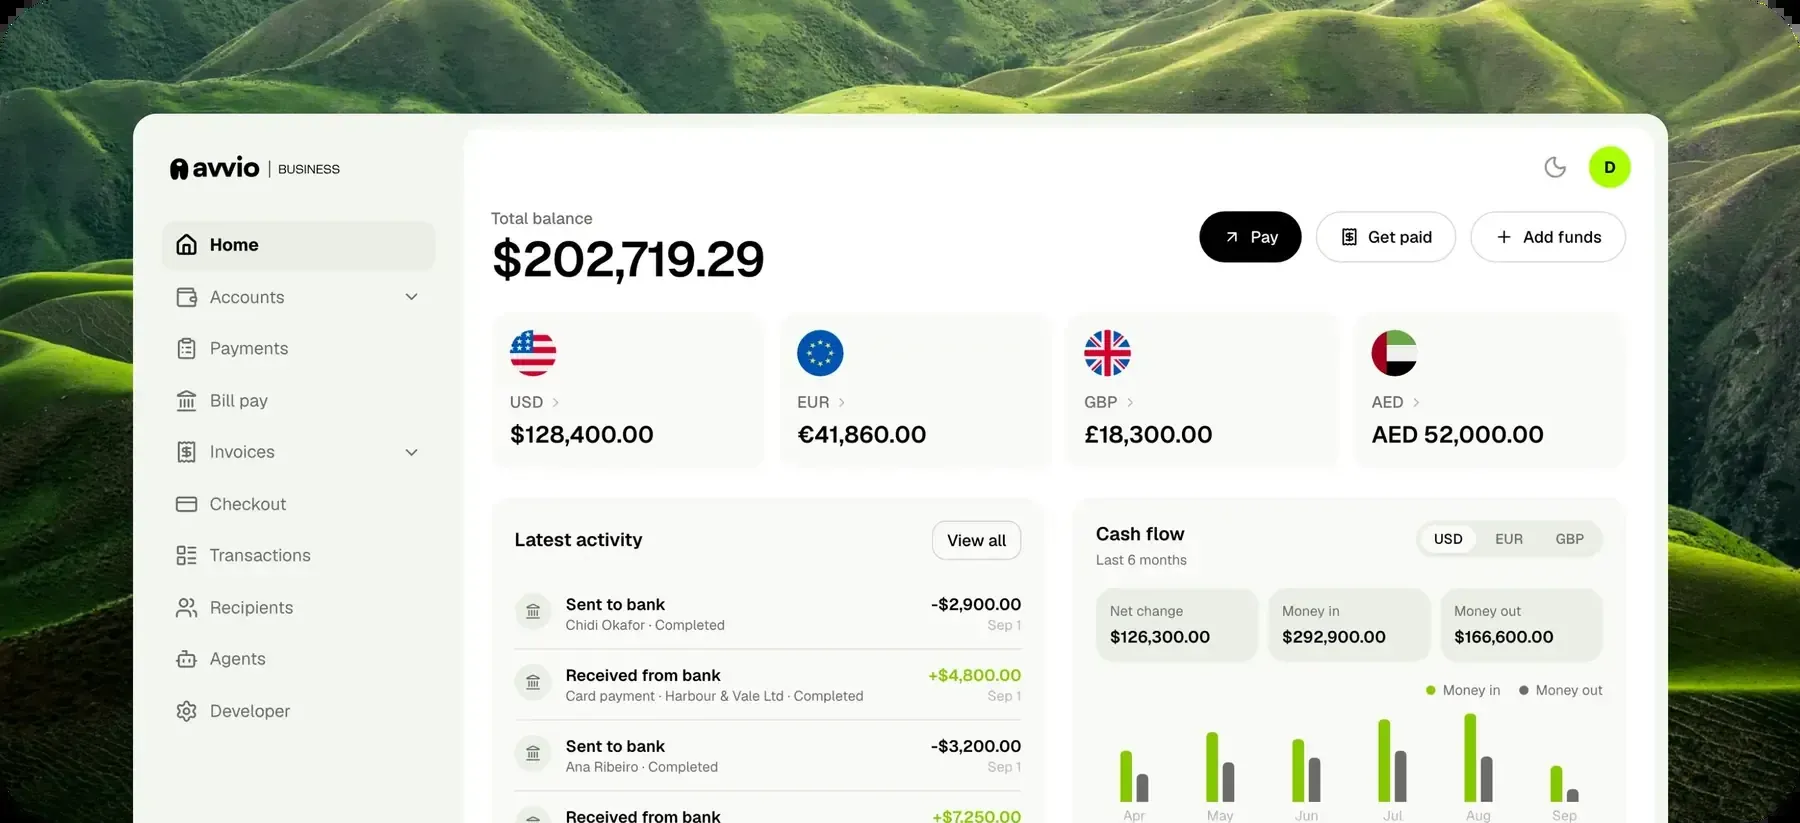
Most providers only do payouts. A business also needs to get paid, so the product does both, and the design puts them on the same feed.
Get paid
Real local account details in four currencies, so customers pay like they would a domestic supplier. The details never change: put them on the invoice once and stop chasing wire instructions. Funds land in an account only the business controls. No held balances, no payout schedules, no freezes.
Pay
The right rail for every payout: Pix and UPI, PayPal and Venmo balances, push to card, and SWIFT when it’s the right call. Price and send happen in one step, and if the rate moves past the agreed tolerance before sending, nothing is sent.
Close the month
Money in and money out land on one timeline, already reconciled. Every movement carries its counterparty, rate and status, so month-end is an export, not a project.
07 Mass payouts
Payday can’t fail
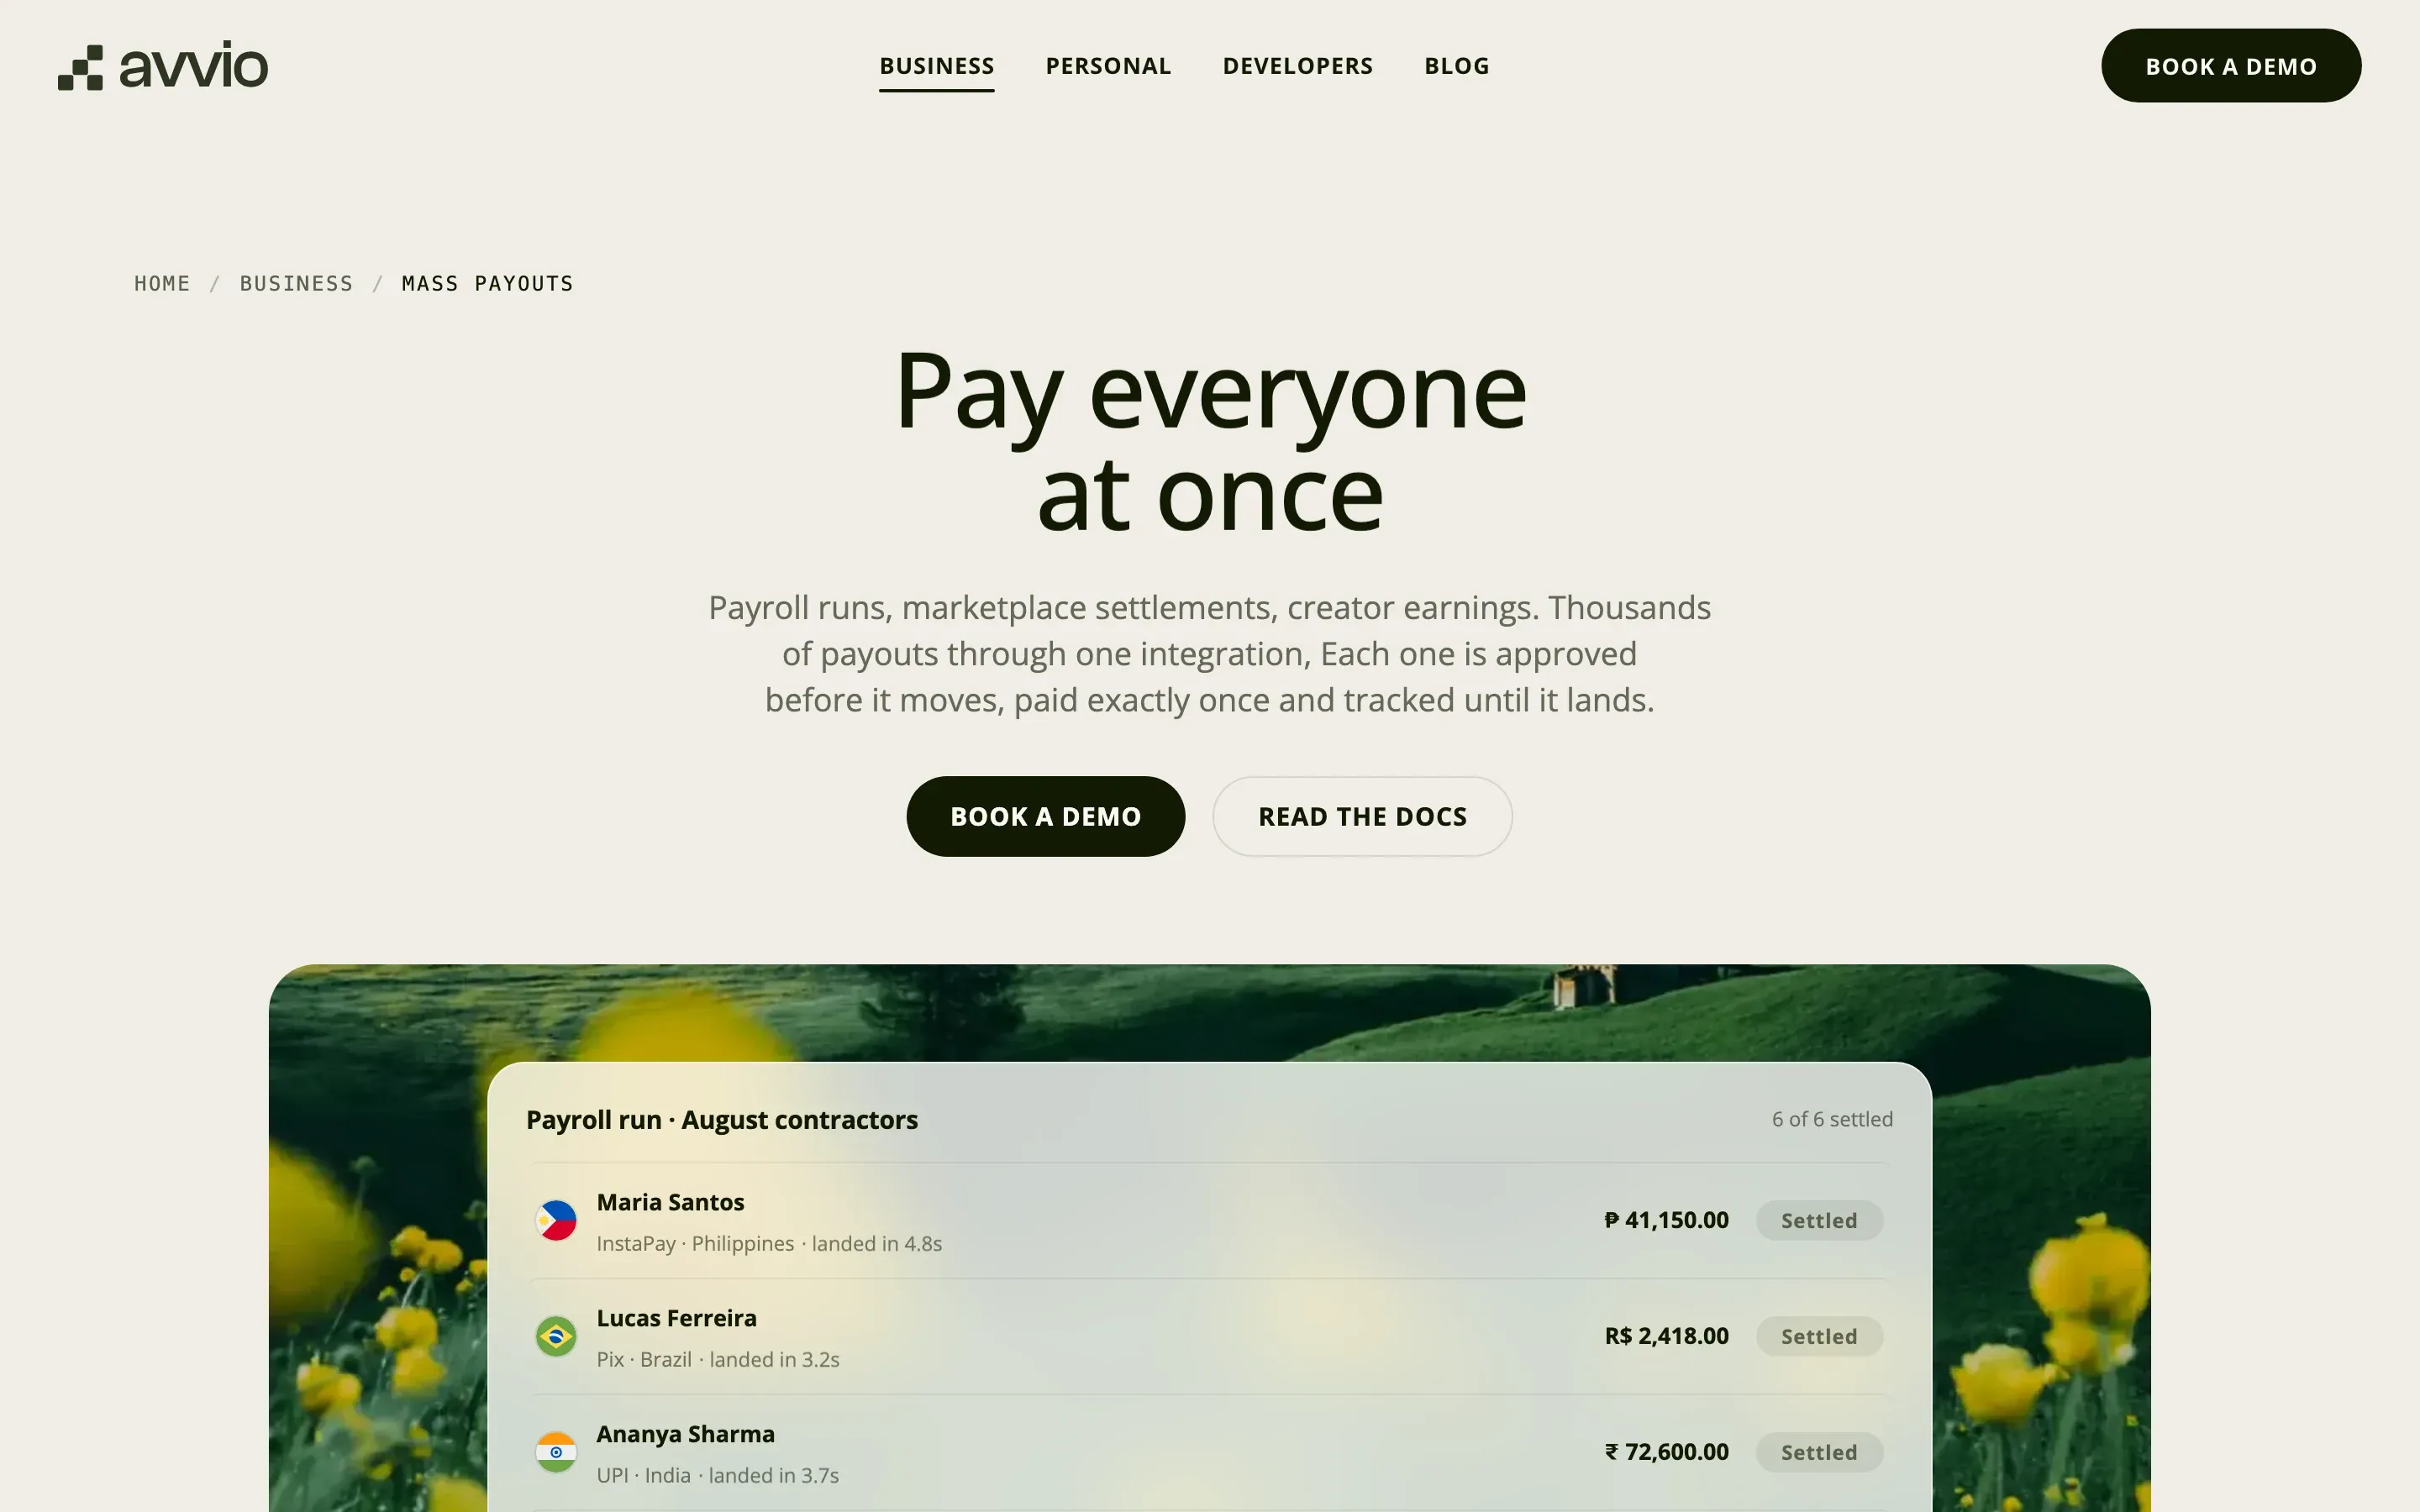
Payroll runs, marketplace settlements, creator earnings: thousands of payouts from one approval. At that volume the guarantees matter more than the features, so the interface is built around them:
- A retry can’t become a second payment. Every payout carries an idempotency key; a timeout mid-run replays cleanly.
- The rate can’t drift. Send the amount promised to the recipient; if the rate moves past tolerance, nothing leaves.
- Two approvals before money moves, with roles deciding who can send, how much and to whom.
- A strict five-state lifecycle, shown as a live run where each payout ticks from queued to landed, with the seconds it took.
- No bank details? Send a link. Recipients enter their own account on a hosted page, so the business never touches the data.
08 Rails
Where money lands, and what you need
Trust in cross-border payments comes from specifics. Instead of “150+ countries”, the site publishes every rail: the network, how fast it lands, and the one detail you need from your recipient.
16 rails, settling on local networks
| Destination | Network | Speed | What you need | Currency |
|---|---|---|---|---|
| Brazil | Pix | Instant | Pix key or CPF | BRL |
| India | UPI | Instant | UPI ID or account + IFSC | INR |
| Mexico | SPEI | Instant | CLABE | MXN |
| Philippines | InstaPay | Instant | Bank account or e-wallet | PHP |
| Nigeria | NIP | Instant | NUBAN account | NGN |
| UK | Faster Payments | Instant | Sort code + account | GBP |
| Indonesia | BI-FAST | Instant | Bank account number | IDR |
| Thailand | PromptPay | Instant | PromptPay ID or account | THB |
| Hong Kong | FPS | Instant | FPS ID, phone or account | HKD |
| Europe | SEPA | Same day | IBAN | EUR |
| US | ACH & wire | Same day | Routing + account | USD |
| UAE | Local transfer | Same day | IBAN | AED |
| PayPal | Balance transfer | Instant | Their PayPal email | Local |
| Venmo | Balance transfer | Instant | Their Venmo handle | USD |
| Push to card | Visa Direct | Instant | Their debit card | Local |
| SWIFT | Bank to bank | Same day | IBAN or account + BIC | Any |
Everywhere else settles by SWIFT: payouts reach 150+ countries and 60+ currencies.
09 Developers
The API is a product too
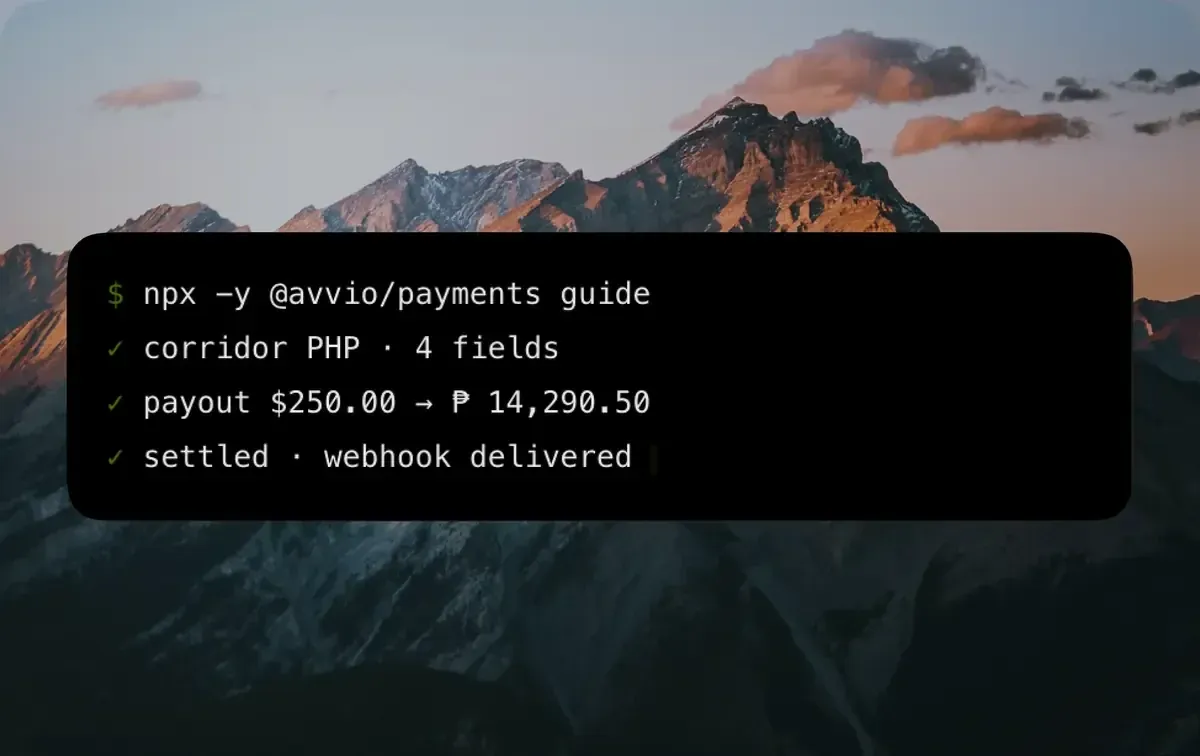
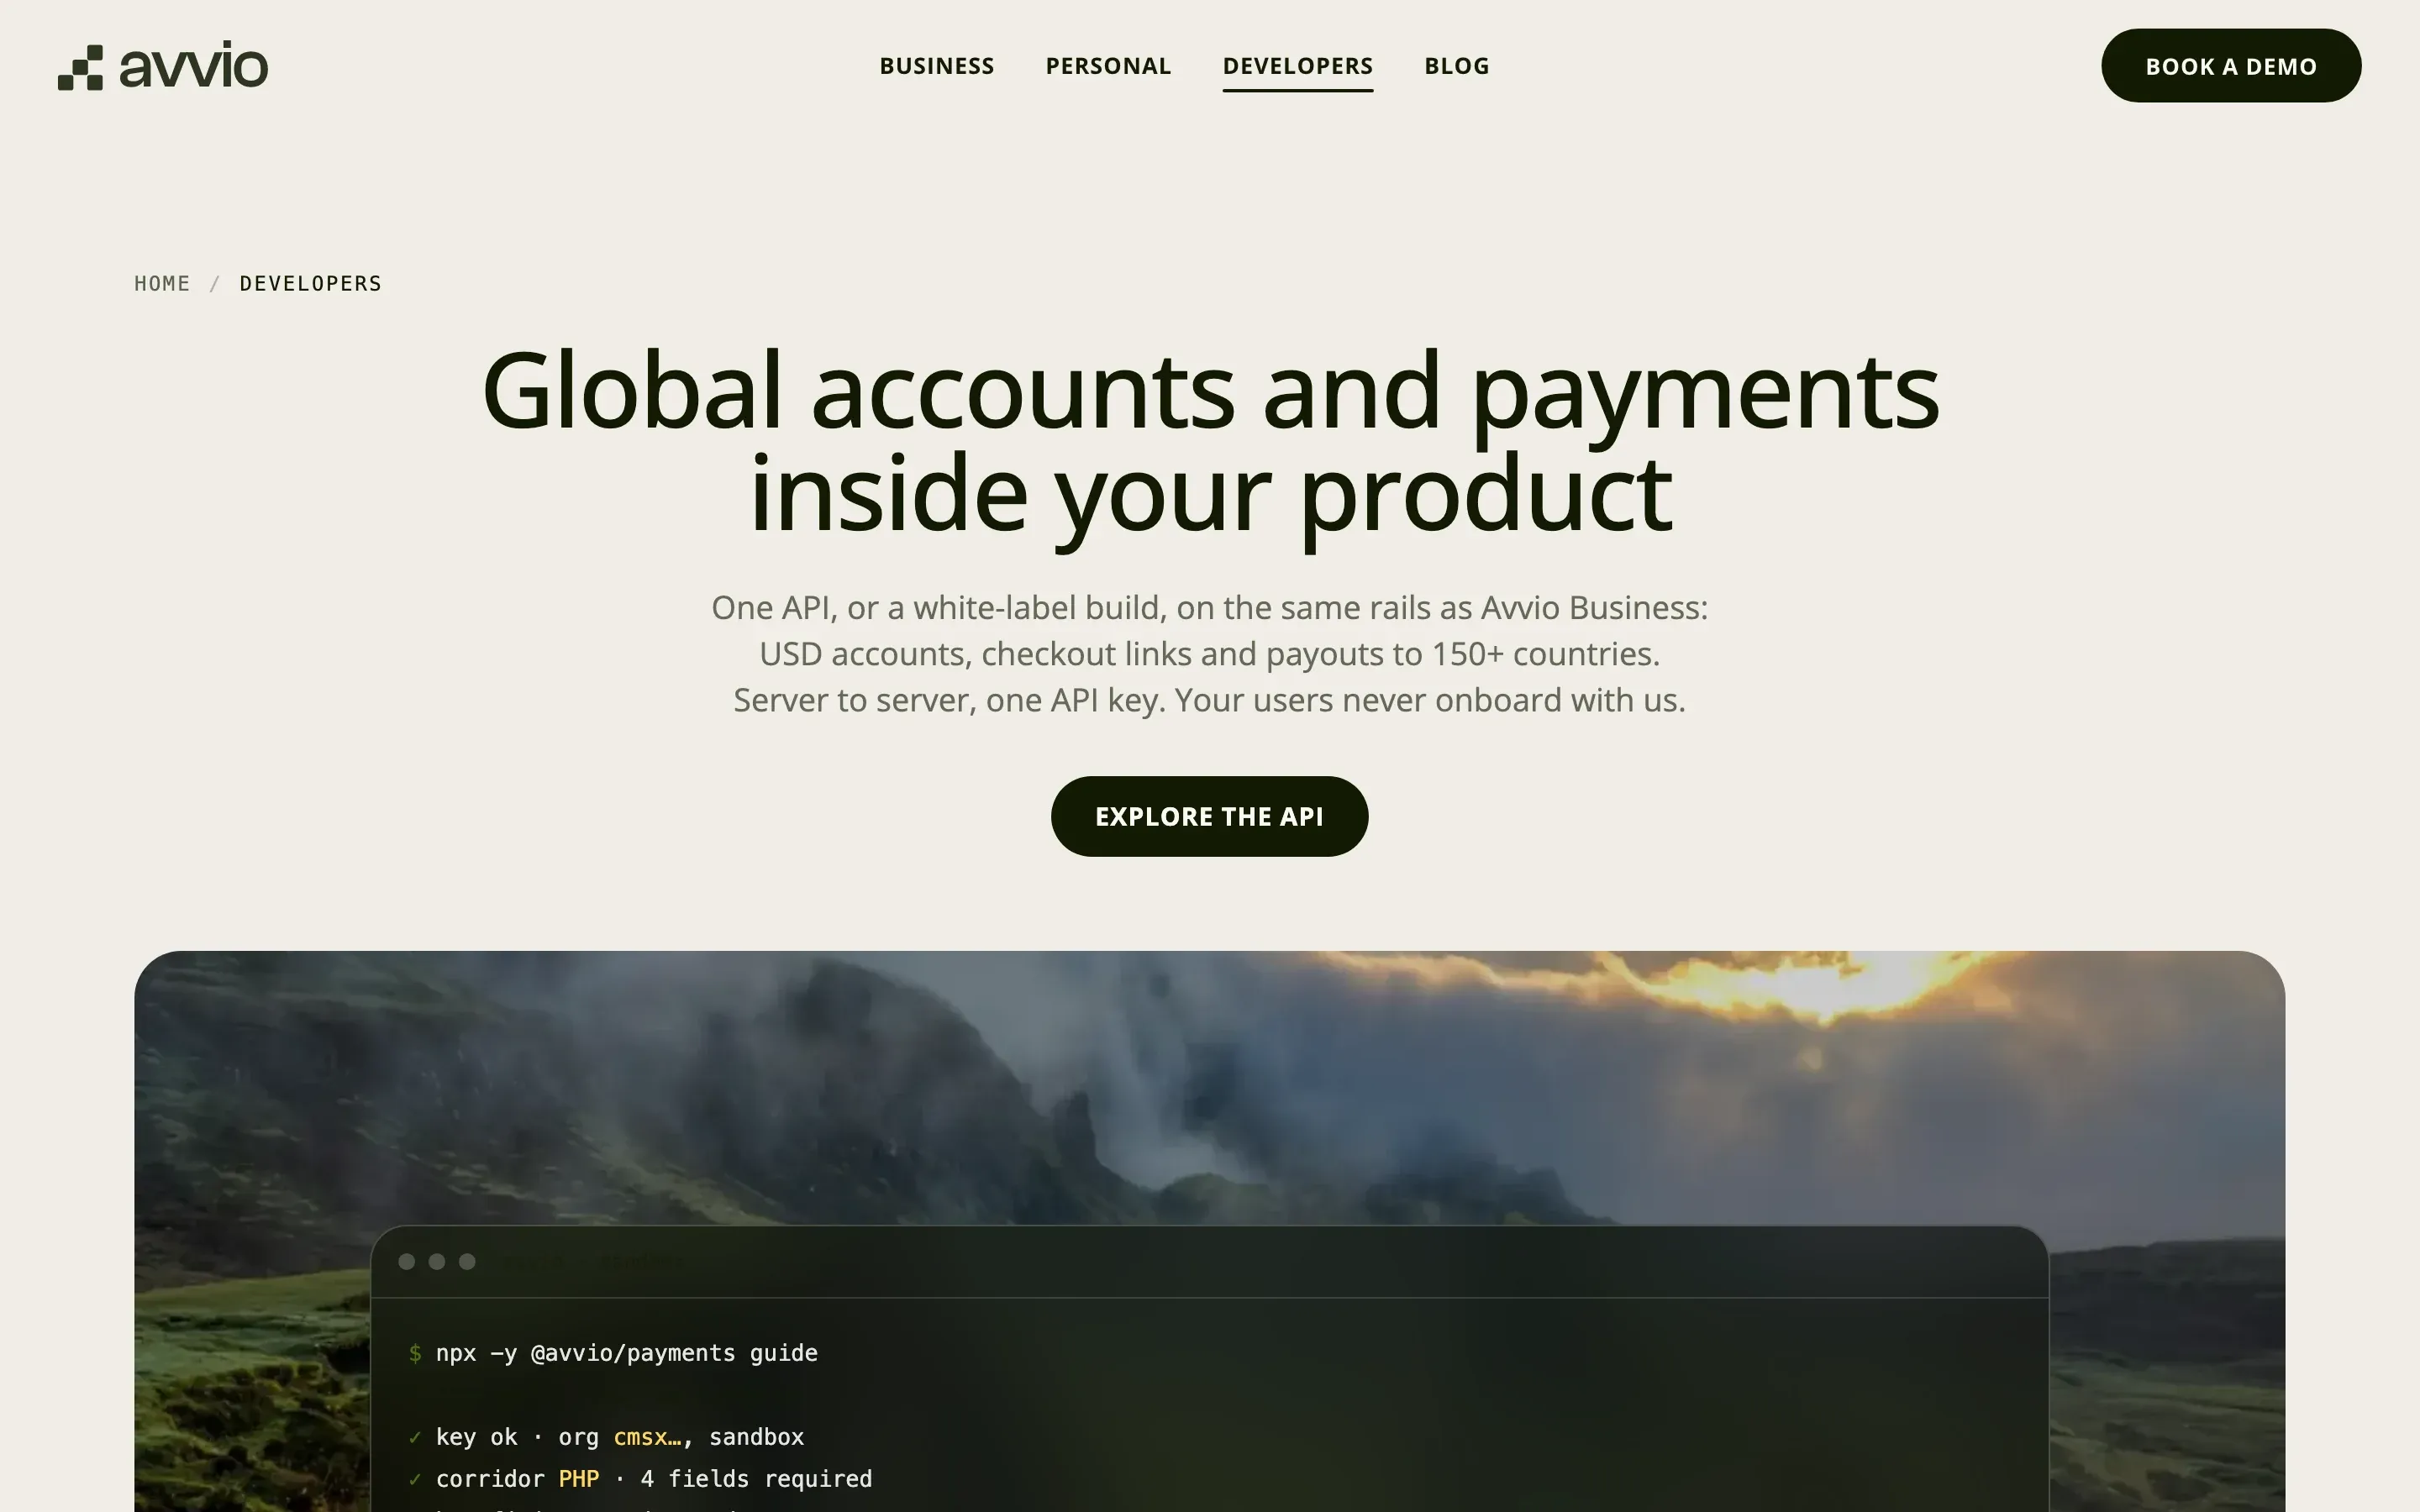
The same rails, sold as infrastructure: one API key, server to server, with USD accounts, checkout links and payouts to 150+ countries. The developer page leads with a working terminal flow, from key check to settled webhook, because developers trust what they can run.
10 Growth
A partner program that does the maths
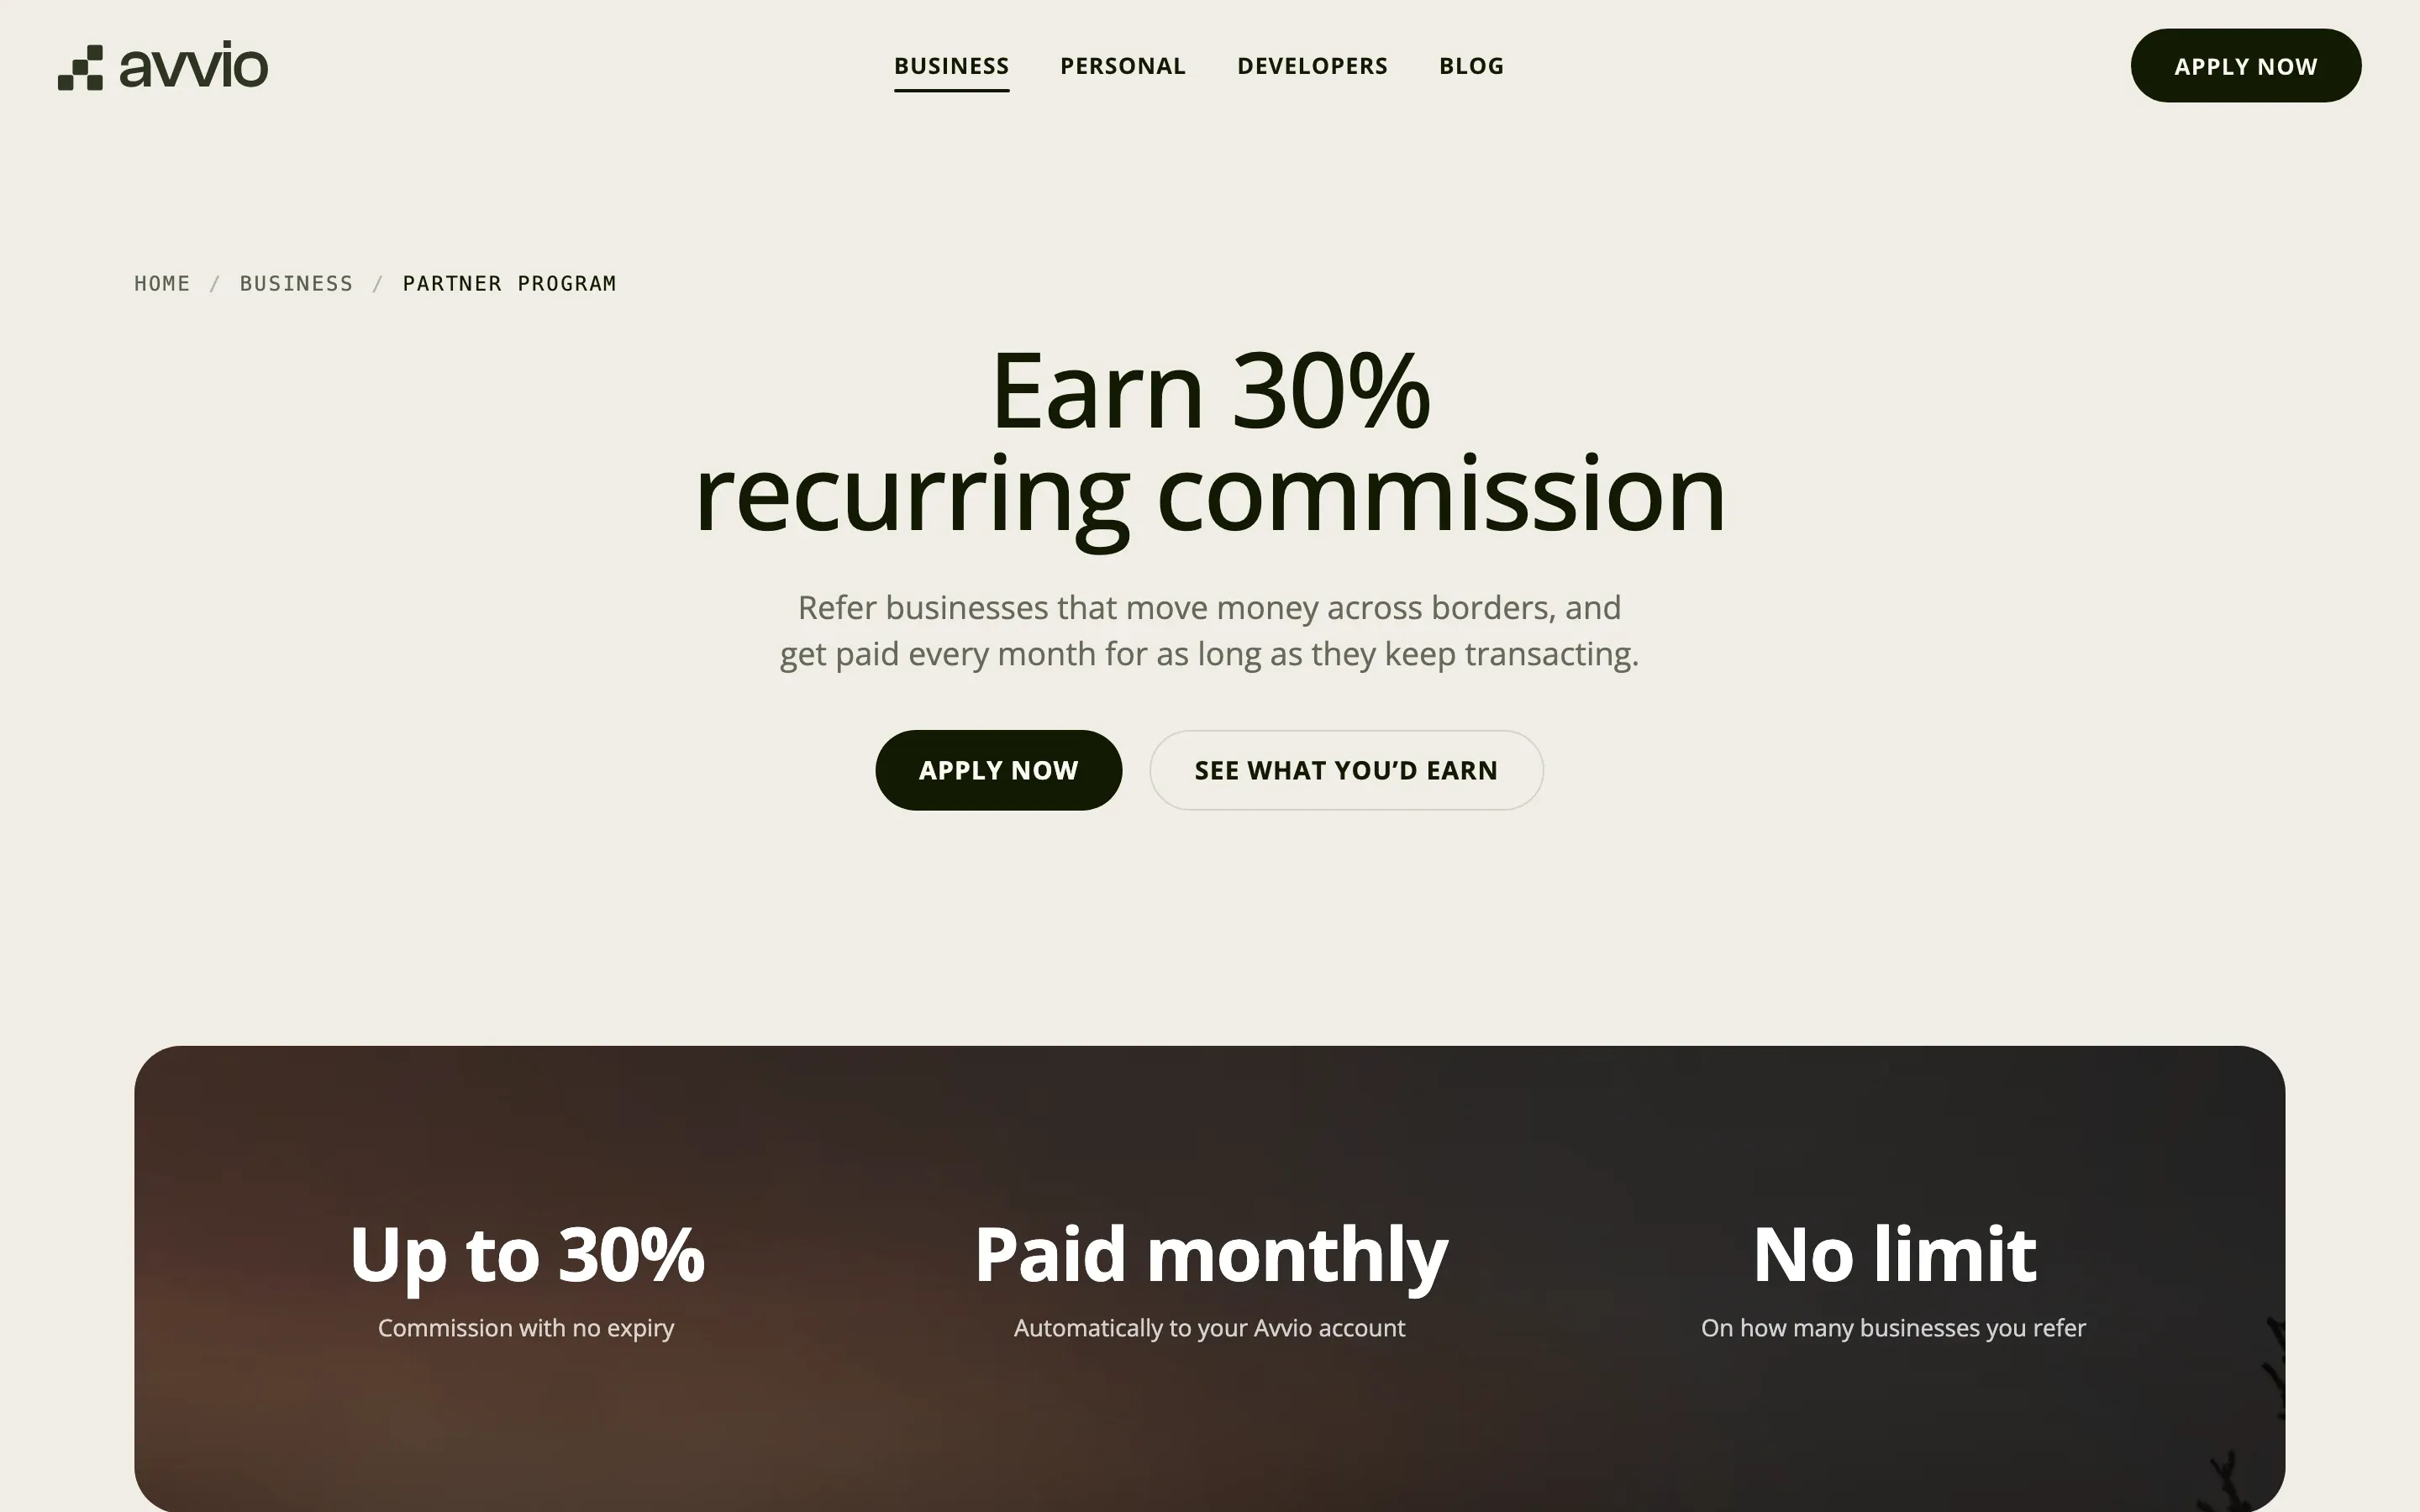
Growth runs on referrals from the people who already know businesses that move money across borders. The partner page pays 20% recurring commission, rising to 30% in any month a referral moves $100,000 or more, and lets partners model their own earnings with a calculator before they apply.
11 Trust
How the money stays safe
For a finance team, the security model is part of the product. Three promises, stated plainly on every page that asks for money.
Your balance, your say
Businesses keep custody of their money. Avvio moves payments; it doesn’t hold balances.
Licensed partners on every corridor
Every busy corridor runs through more than one licensed partner, so one going down doesn’t stall a payout.
Passkeys and approvals
Payments need a passkey login and whatever approval rules the team sets. One unlocked laptop can’t send a run.
12 Website
avvio.xyz
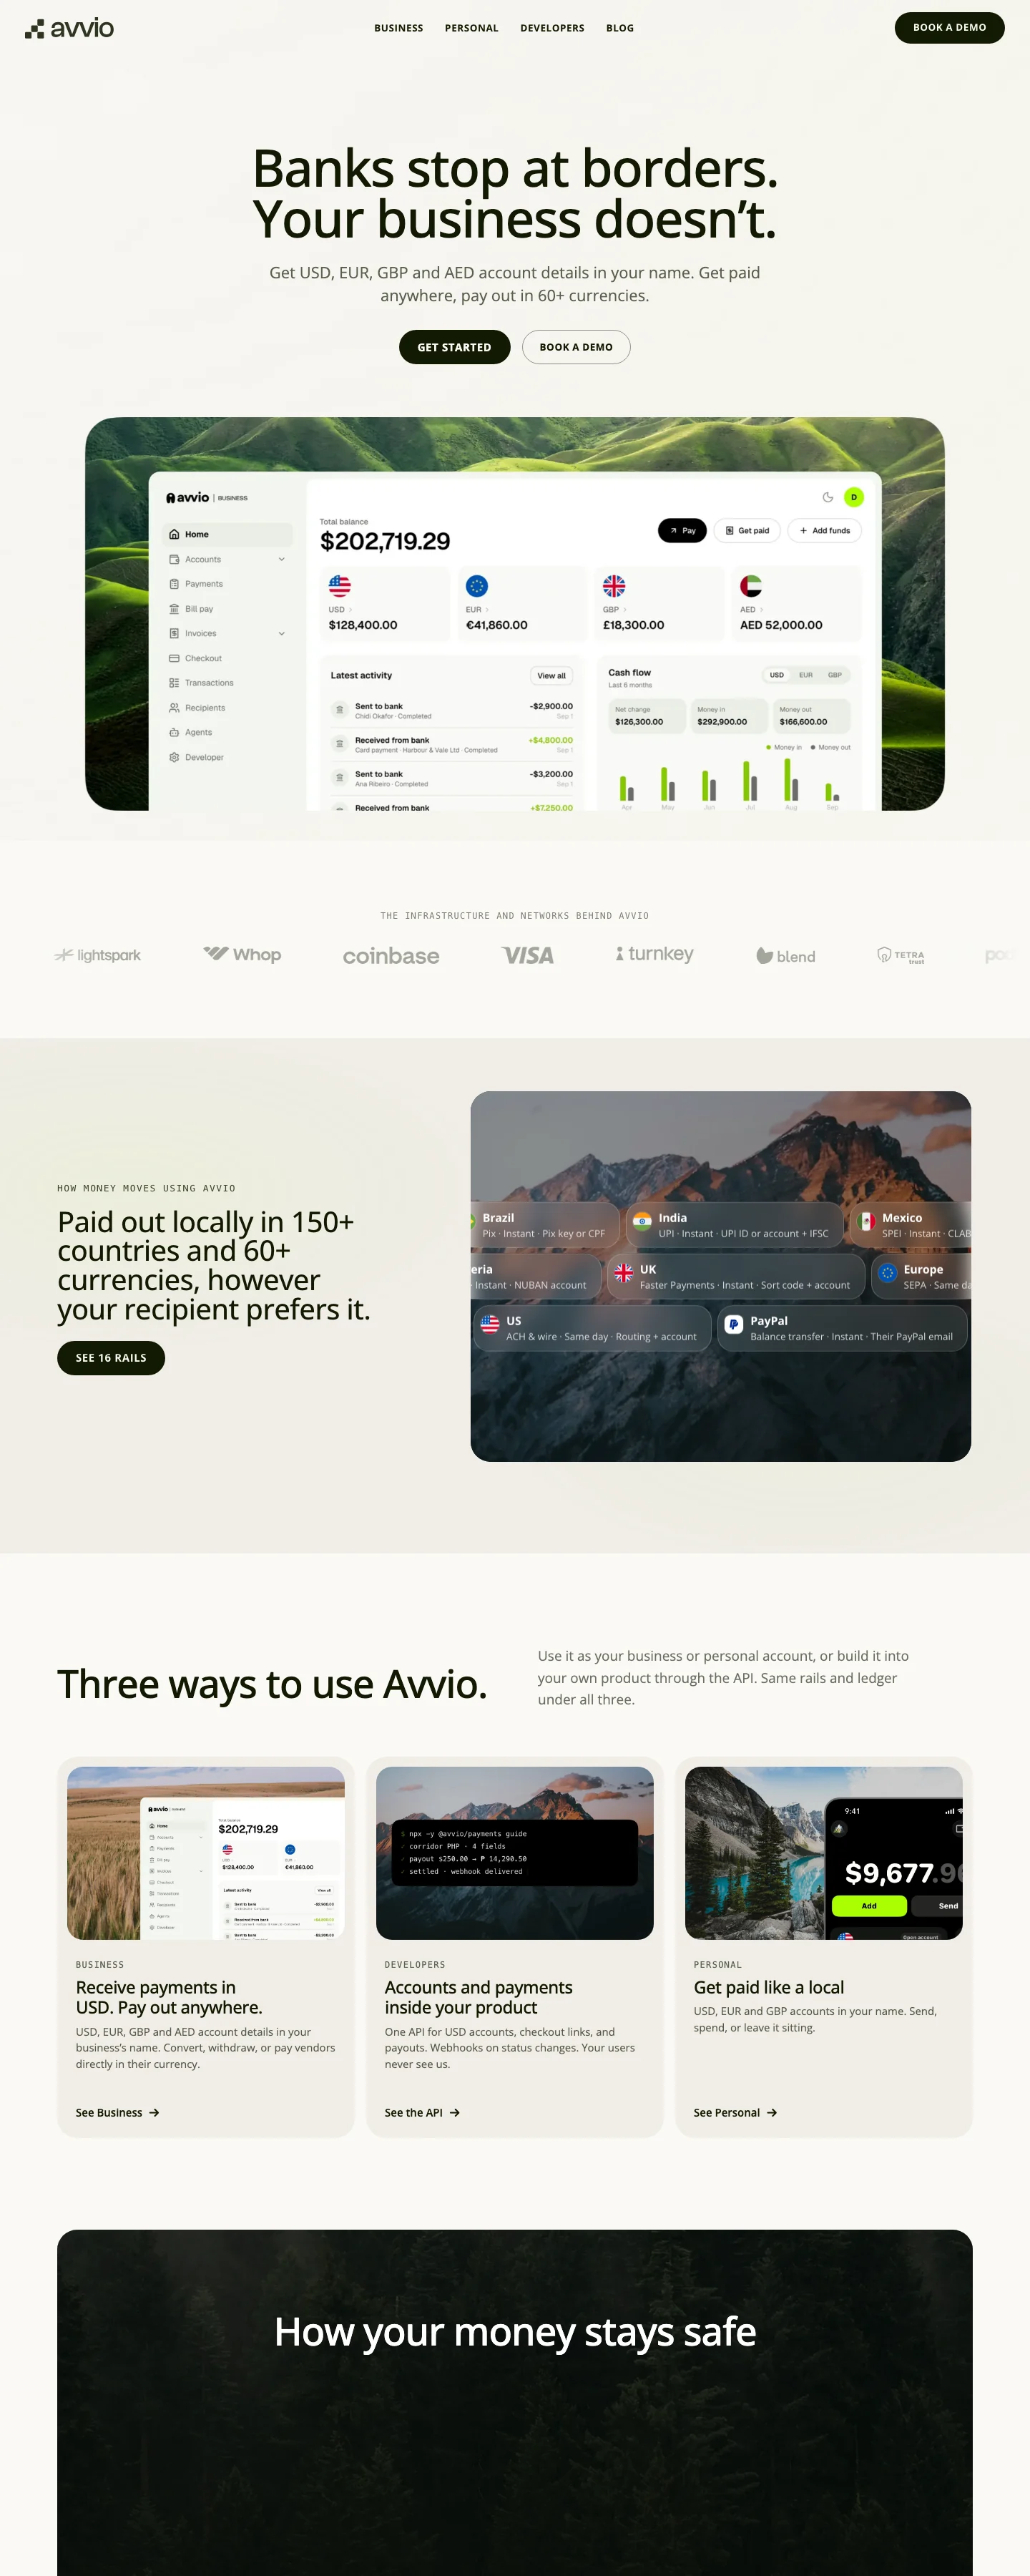
The site is the guidelines in use: cream grounds, ink type, one product screenshot doing the selling, and partners like Visa, Coinbase and PayPal as quiet proof. Scroll the full homepage below.
Outcome
A queue, not a funnel
Businesses are waiting in line to onboard. The product is audit-ready for SOC 2 Type II and ISO 27001, which matters as much to a finance team as any screen.
Read how the consumer app launched in the Avvio case study.